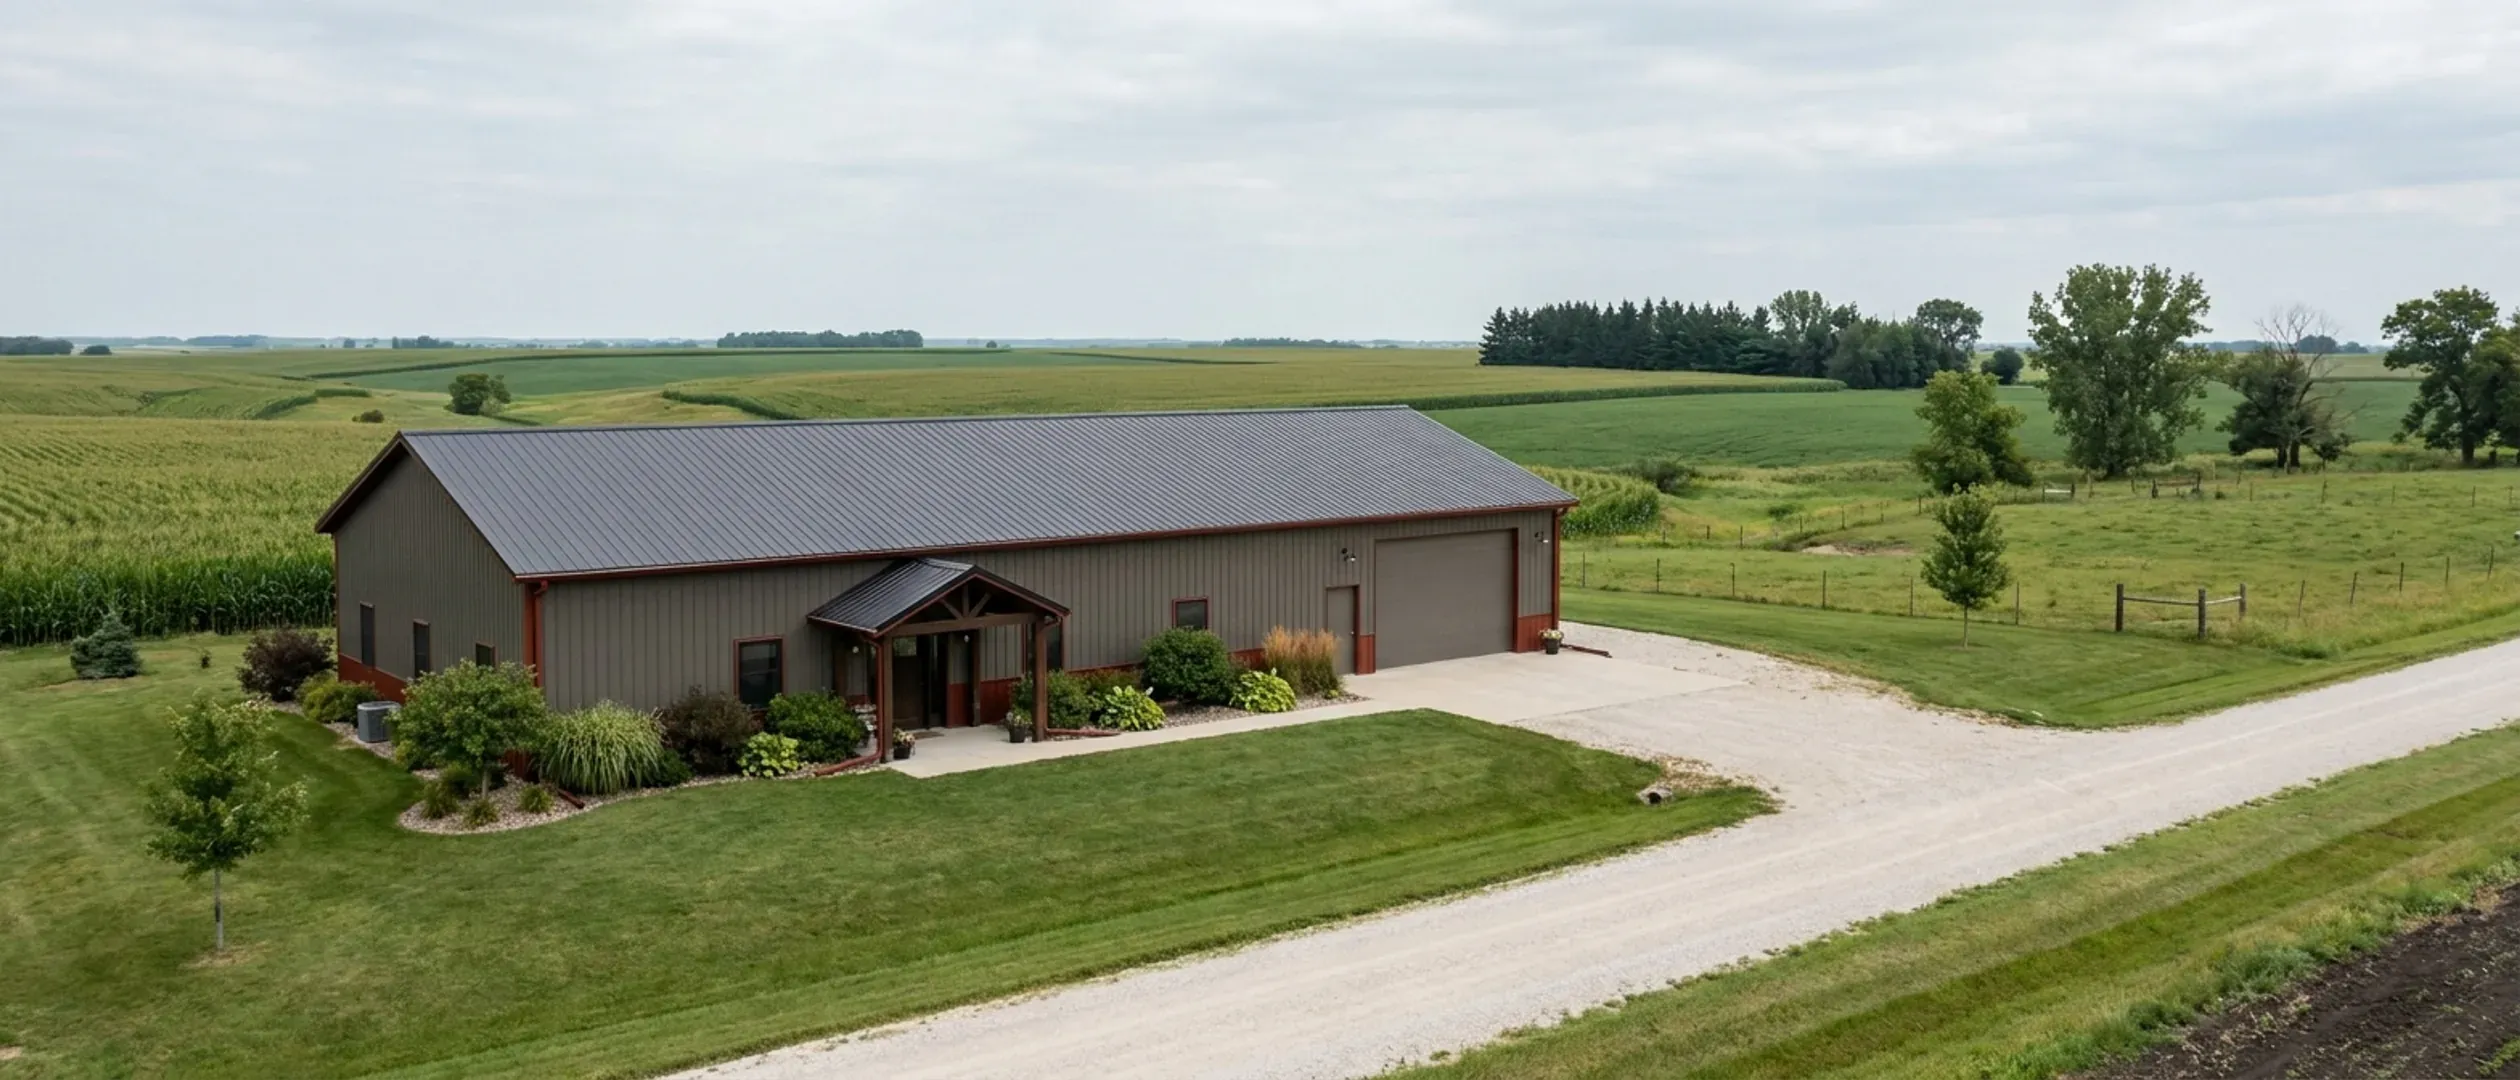
Barndominium Financing in Iowa: Construction Loans, USDA and Farm Credit
A barndominium is financed the way most custom homes are: a construction loan that pays the builder in draws while the home goes up, then a permanent mortgage once it is finished, sometimes rolled into a single closing. What makes a barndominium different is not the loan type but the underwriting. The lender has to be satisfied that the finished property is a home with a reliable market value, and a building that combines living space with a large shop on rural land asks harder questions than a house in a subdivision. This guide covers the programs available to Iowa buyers, from USDA Rural Development and Farm Credit to the Iowa Finance Authority, with the rules each one publishes, and the parts of a barndominium plan that affect whether a lender says yes.
Figures on this page are cited third-party or government data, not a quote from Iowa Barndominium Builders.
Bottom Line Up Front
- Most custom homes are financed with a construction loan that converts to a mortgage. Farm Credit Services of America's Rural 1st brand, which lends in Iowa, says it finances barndominium builds with a one-time close and allows up to a year to finish.
- USDA Rural Development's programs can finance building a home in an eligible rural area, but federal rules bar using the money for income-producing buildings, and the direct program's site may not include farm service buildings. A big working shop needs to be discussed up front.
- The appraisal is the step to plan for. Fannie Mae's Selling Guide treats unusual homes case by case and says significant outbuildings may indicate a property is agricultural rather than residential.
What actually moves the number
The appraisal
The loan amount follows the appraised value. Fannie Mae's Selling Guide says unique homes are eligible when the appraiser has enough information for a reliable value, decided case by case, so comparable sales in your county matter.
The shop
Federal USDA rules exclude income-producing buildings, and Fannie Mae's guide says large outbuildings may make a property look agricultural. How the shop is described and used affects which loans fit.
The land
Owning the land helps. Farm Credit Services of America's construction-loan page says it counts the equity in your land toward the down payment. USDA's direct program limits the site to one that cannot be subdivided under local zoning.
The builder
Construction lenders approve the builder as well as the borrower. FCSAmerica's page says you choose your own builder, provided the builder meets its requirements.
How Midwest custom homes are actually paid for
The Census Bureau reports how contractor-built homes, the category a barndominium on your own land falls into, were financed.
Mostly conventional loans
Of the contractor-built homes started in the Midwest in 2025, 66% were financed with conventional loans, per the Census Bureau's Survey of Construction. FHA-insured loans were 2% and VA-guaranteed loans 1%.
Almost a third paid cash
31% of Midwest contractor-built homes started in 2025 were built for cash, per the Census Bureau. Many owners who build on land they already hold fund some or all of the construction themselves.
What the loans had to cover
The Census Bureau reports a median contract price of $457,200 for Midwest contractor-built homes started in 2025, not counting the land. Our Iowa barndominium cost guide breaks that down.
One closing or two
A two-close plan uses a short-term construction loan, then a separate mortgage when the home is done. A one-time close, or construction-to-permanent loan, sets both up at once. A one-time close means one set of closing documents instead of two; the two-close route lets you shop the mortgage after the home is built.
Farm Credit and rural lenders
Farm Credit associations lend on rural property, including acreages and homes on them. In Iowa that is Farm Credit Services of America, which serves Iowa and three neighbouring states.
Barndominiums named outright
Farm Credit Services of America's Rural 1st construction-loan page says that, in addition to conventional-style homes, it finances barndominium and log home builds, with a one-time close and up to one year to complete the project.
Land equity toward the down payment
The same page says it counts the equity in your land, its outbuildings and other site improvements toward the down payment on a construction loan, which can lower what you need to put down.
Land first, then the house
FCSAmerica's rural home loan page describes financing for buying land and constructing a home, and for adding outbuildings and improvements over time, so the land purchase and the build can be planned with one lender.
Local banks and credit unions
Iowa banks and credit unions also make construction loans. Terms vary lender by lender, so ask each whether it has financed barndominiums before and how it appraises and inspects one.
USDA Rural Development
USDA's single-family programs apply in eligible rural areas of Iowa. Both can pay for building a home, and both have rules that bear directly on a barndominium with a shop.
Direct loans can build and prepare the site
USDA's Section 502 Direct program page for Iowa says funds can be used to build, repair, renovate or relocate a home, or to purchase and prepare sites, including providing water and sewage facilities. It is for low- and very-low-income applicants, and as of 1 September 2026 USDA lists its rate at 5.250%, with terms up to 33 years.
Guaranteed loans can be one-time close
Under 7 CFR 3555.101(c), USDA will guarantee a combination construction and permanent loan for a home that will be the borrower's principal residence, which is the single-close structure most custom builds use.
No income-producing buildings
The direct program page says financed property must not be designed for income-producing activities, and 7 CFR 3555.201 says a guaranteed-loan site must not include buildings used principally for income-producing purposes. A shop run as a business is the part of a barndominium USDA will look at.
Site size and farm buildings
For direct loans, 7 CFR 3550.56 says the site must not be large enough to subdivide under local zoning and must not include farm service buildings, though small outbuildings such as a storage shed may be included. For guaranteed loans, 7 CFR 3555.201 says the site size must be typical for the area.
The appraisal: the step to plan for
A lender lends against value, and value comes from the appraisal. For a barndominium this is where a loan most often gets complicated, and most of it can be anticipated.
Unique homes are eligible, case by case
Fannie Mae's Selling Guide says loans on unique or nontraditional housing are eligible when the appraiser has adequate information to develop a reliable opinion of market value, and that the appraiser and the underwriter each decide that independently, case by case.
Comparable sales do not have to match
The same guidance says comparable sales need not be of the same design as the home being appraised, though the most similar sales give the most accurate result. Where few barndominiums have sold nearby, the appraiser can work from conventional homes and adjust.
Large outbuildings raise a question
Fannie Mae's guide says significant outbuildings, such as large barns or storage areas, may indicate that a property is agricultural in nature, and the lender must decide whether it is residential. Describe a shop as part of the home, sized for the household's use, and discuss it with the lender before the plan is final.
Give the appraiser what they need
A complete plan set, a finish schedule and a line-item budget let the appraiser value the finished home instead of guessing at a metal building. If your county has recorded barndominium sales, point your lender to them.
The Iowa Finance Authority
IFA's homeownership programs are aimed at buying a home. They are worth knowing about, and worth asking a participating lender about, but they are not construction loans as published.
FirstHome
IFA's FirstHome page lists a 2026 household income limit that varies by county and household size, from $102,100 to $171,360, and a home purchase limit of $566,000, up to $692,000 in targeted areas. Buyers must generally be first-time buyers, meaning they have not owned their primary residence in the last three years.
Homes for Iowans
IFA lists Homes for Iowans for first-time and repeat buyers, with a 2026 household income limit of $171,360 and a home purchase limit of $692,000. Both programs list a minimum 640 credit score and a maximum 50% debt-to-income ratio.
Purchase only, as published
Both program pages list the allowable terms as new purchase only, no refinances, on 25- or 30-year terms. Whether a lender can use one for the permanent loan on a home you build is a question for an IFA participating lender, because the pages do not say.
Free owner's title certificate
IFA's program pages say borrowers may request a free Iowa Title Guaranty owner's certificate at closing, which covers the cost of defending the owner's title if a covered defect arises.
Reading this because you are weighing a build? The next step is a plan drawn for your program.
What's different about Iowa
Iowa's title coverage comes from the state
Iowa Title Guaranty, which the state publishes under the Iowa Finance Authority, describes itself as Iowa's exclusive title coverage provider, offering lenders and owners title coverage for Iowa real property. Expect your lender's title requirements on an Iowa construction loan to run through it.
The Iowa Finance Authority's loans are purchase loans
IFA's FirstHome and Homes for Iowans programs both list their loan terms as new purchase only, with no refinances. The program pages do not describe a construction product, so ask an IFA participating lender whether either can be used for a home you are building.
The farm-house exemption and USDA pull in opposite directions
Iowa Code § 335.2 exempts a farm house on a working farm from county zoning. USDA's guaranteed program, under 7 CFR 3555.201, treats property used primarily for agriculture as ineligible. A home that leans on the farm exemption may not suit USDA financing, and the reverse.
Permits depend on the jurisdiction, and lenders ask
Iowa's building code applies only where a city or county has adopted it, so some rural Iowa builds have no building permit or inspection. A lender's draw inspections still happen, and FCSAmerica's page describes tracking draws, disbursements and inspections through the build, but a lender's inspection is not a code inspection.
Can you get a mortgage for a barndominium in Iowa?
Can I use a USDA loan to build a barndominium in Iowa?
Does the Iowa Finance Authority finance barndominium construction?
How much down payment do I need for a barndominium construction loan?
Why is a barndominium harder to appraise?
Will a big shop cause problems with my loan?
Can I use my land as the down payment?
Where do I start?
Questions answered? Tell us what you want to build and we will put real numbers against it.
Sources
- USDA Rural Development — Single Family Housing Direct Home Loans in Iowa — Uses of funds, income-producing exclusion, 5.250% rate effective 1 Sep 2026; page rendered 26 Sep 2026
- 7 CFR 3555.101 — Loan purposes (USDA guaranteed loans) — (c) combination construction and permanent loan
- 7 CFR 3555.201 — Site requirements (USDA guaranteed loans)
- 7 CFR 3550.56 — Site requirements (USDA direct loans)
- Farm Credit Services of America — Rural Construction Loans (Rural 1st)
- Farm Credit Services of America — Rural 1st Home Loans
- Iowa Finance Authority — FirstHome Program
- Iowa Finance Authority — Homes for Iowans
- Iowa Title Guaranty
- Fannie Mae Selling Guide B4-1.3-05, Improvements Section of the Appraisal Report — Unique Housing Types; Properties with Outbuildings
- U.S. Census Bureau — Contract Price of New Contractor-Built Houses Started, by Region and Type of Financing — Midwest 2025: 66% conventional, 31% cash, 2% FHA, 1% VA; median contract price $457,200
- Iowa Code § 335.2 (PDF)
Keep reading
The pages that answer the next question this one raises.
What a barndominium costs in Iowa
The Census and NAHB figures a lender's budget review will be measured against.
Read itHow big a barndominium your budget builds
Turning a loan amount into a realistic size, after the land and site costs.
Read itBarndominium vs. house cost in Iowa
Including why appraisal and resale belong in the comparison.
Read itBarndominium floor plans with a shop
The layouts where how the shop is sized and described matters most to a lender.
Read itWant a real number instead of a range?
Start the survey and tell us about your land and what you want to build. Include the county and parcel ID if you have them, because in Iowa the jurisdiction, the soil and the well and septic answers change the budget more than the building does. The survey costs nothing.